Setting your rates as a freelancer isn't about copying an old salary. You calculate them backwards, starting from what you actually want to earn. You'll see how to get from your target net income to your floor average day rate (TJM), with a worked example. You'll also learn how to hold that price against the market and AI, and what changes for your taxes when you move abroad. The social contribution figures below apply to the French micro-entreprise.
Why a Freelance Rate Is Calculated Backwards
Many new freelancers take their old salary and divide it by the number of days in the month[1]. That's a costly mistake: neither charges nor slow days are part of that calculation[1].
As a freelancer, your revenue is not your net income. You have to account for social contributions, professional expenses, unbilled days, and the time spent prospecting, training, or running your business[2]. The principle fits in one sentence: to set your rates, start from what you need to earn, not from what others charge[3].
How Many Billable Days a Year
Not every working day can be billed to a client[4]. A beginning freelancer typically bills between 120 and 150 days a year: you need to account for prospecting, training, admin, the vacation nobody pays you for, and weeks without a mission[1].
The lower this number, the higher your day rate has to be to hit your income target[4]. Assuming 220 billable days when you will actually bill 150 undervalues your TJM by roughly 27%[1].
Charges and Contributions to Include
In a micro-entreprise for non-commercial service activities, you pay 25.6% of your revenue in social contributions in 2026[1]. This rate applies from the first euro collected, with no deduction of expenses beforehand[1].
Contributions are calculated differently under a micro-entreprise, a sole proprietorship, an EURL, or a SASU, each with its own level of deductions[4].
Add the expenses beginners almost always forget: supplementary health insurance, professional liability insurance, an accountant or invoicing software, and the business property tax (CFE)[1]. Together, these typically come to €4,000 to €8,000 a year[1].
Under a micro-entreprise, these expenses are not deductible: they come out of your income, so they must be built into your rate[3]. This status mainly suits freelancers with few expenses[4].
The Day Rate Formula, With a Worked Example
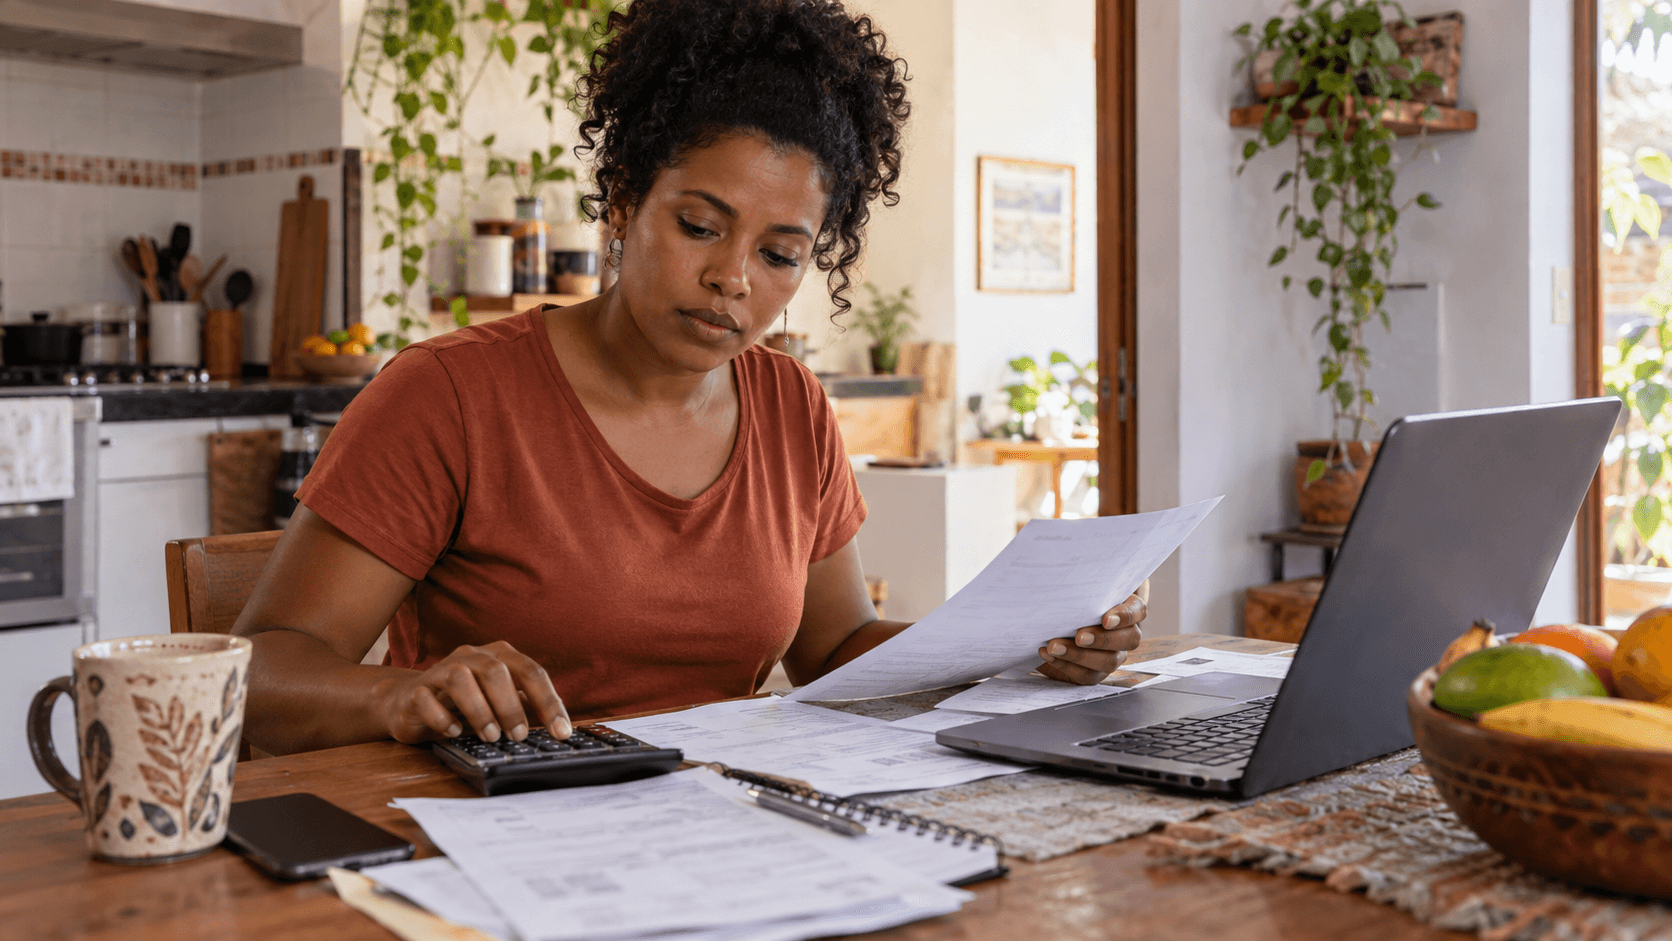
The formula is: required annual revenue = (target annual net income + additional expenses) / (1 − 0.256), then TJM = required annual revenue / billable days[1].
Example: you aim for €2,300 net per month, or €27,600 over the year, and you expect €5,000 in additional expenses. You then need to bill about €43,800 in revenue over the year[1]. Spread across 140 billable days in a first year, that gives a TJM of about €313[1].
For small assignments, the hourly rate is derived from the TJM: divide it by 7[3].
This figure is your floor, the rate below which you lose money, before income tax, which the formula does not deduct: keep a margin to pay it[3]. Your actual price is set above that, based on the market and the value you deliver[3]. You can also adjust it according to your experience and expertise[4].
Holding Your Price: Market, Negotiation, and AI Competition
Once your floor is calculated, compare it to the day rates in your field, then state it with confidence[3]. If your floor exceeds the top of your field's range, don't lower your rate first: instead, review your expenses, your number of billable days, your status, or your target clients[3].
When a client wants a lower price, negotiate the scope, not the price[3].
Your Profession Matters as Much as Your Rate
- Writing and editing: the most asynchronous profession of all; the constraint is not mobility but falling income linked to AI[5].
- Translation and localization: also highly asynchronous, with a shrinking-work constraint linked to AI (post-editing of machine translation)[6].
- Content creation: workable as a digital nomad, provided you have a reliable connection, since uploads are heavy and regular[7].
- Video editing and motion design: heavy footage to transfer and powerful editing hardware, so bandwidth and equipment need to be planned[8].
Pitfalls and Points of Caution
- Confusing revenue with income: social contributions apply from the first euro collected[1], and under the micro-entrepreneur regime, business expenses are not deductible[3].
- Forgetting side costs (health insurance, liability insurance, accountant, business property tax): your day rate would be structurally too low, even with a perfect formula[1].
- Overestimating your billable days: 220 days instead of 150 undervalues your rate by about 27%[1].
- Combining employment with self-employment without reading your contract: combining the two is legal in France, but an exclusivity clause, a non-compete clause, or your duty of loyalty may limit your project, and failing to comply may lead to dismissal[2].
- Exceeding the micro-entrepreneur ceiling without planning ahead: it is €83,600 in annual revenue for service activities, and exceeding it may point you toward another legal structure[2].
- Neglecting your tax residence when leaving: it determines which income you are taxed on (see the next section).
- Forgetting to declare bank accounts opened abroad, an obligation detailed below.
Income Abroad: Tax Residence and Declarations
This section is aimed at people leaving France; the rules of your country of departure may differ, and taxation requires you to check your personal situation with the tax authorities.
If your tax residence is outside France, you are most often taxable only on your French-source income[9]. If your tax household remains in France, you must pay your income tax there, including on your foreign-source income[9].
Your household (spouse or civil partner and children) remaining in France, or the center of your economic interests in France, are among the criteria that tie you to France[10].
Even if you pay your taxes in France, check with the tax authorities of your country of residence what your obligations are regarding the income to declare and the taxes to pay[9].
- Accounts abroad: you must disclose the details of bank accounts held abroad, whether still in use or closed, using form no. 3916 attached to your income tax return no. 2042[10].
- Address: notify the Public Finance Center you depend on of your new address abroad as early as possible, without waiting until you file your return[10].
- Double taxation: tax treaties are designed to prevent the double taxation of income sourced in one State and received by a person who is tax-domiciled in another State[10].
Steps, in Order
- Define your target annual net income and calculate your side costs.
- Estimate your billable days: 120 to 150 in the first year[1].
- Calculate the revenue you need, then your floor day rate using the formula.
- Compare this floor to the day rates in your field and adjust your target, status, or expenses if needed[3].
- Set up your business through the one-stop shop, available online for micro-entrepreneurs[11], and open your account on the Urssaf website, which manages your social contributions[11].
- Open a dedicated bank account: it simplifies management, and separating flows becomes necessary once you exceed €10,000 in revenue over two years[11].
- Before leaving the country, check your tax residence, notify your tax office of your new address[10], and find out about your obligations in the host country[9].
Sources
- 1.^ abcdefghijklmnogenaisse.com — Setting your freelance day rate: 3 steps, 2026 rates: “Many new freelancers simply copy their former salary divided by the number of days in the month.” ; “A classic and costly mistake: neither charges nor slow periods are factored into this calculation.” ; “A freelancer just starting out typically bills between 120 and 150 days a year: you have to account for prospecting, training, admin, the vacation nobody pays you for, and the weeks without assignments.” https://www.genaisse.com/blog/freelance-fixer-son-tjm-quand-on-debute (accessed October 21, 2026)
- 2.^ abcportail-autoentrepreneur.fr — Becoming a freelancer: the complete guide to getting started in 2026: “As a freelancer, your turnover is not your net income. You need to account for your social contributions, your professional expenses, your unbilled days, and the time spent prospecting, training, or managing your business.” ; “In France, combining employment with self-employment is legal, but you must check your employment contract. An exclusivity clause, a non-compete clause, or your duty of loyalty to your employer can limit your project, and failing to respect them may lead to dismissal.” ; “The micro-entrepreneur status imposes an annual turnover cap of €83,600 for services, which may point you toward a single-person limited liability company depending on your project.” https://www.portail-autoentrepreneur.fr/academie/solopreneur/freelance/devenir-freelance (accessed October 21, 2026)
- 3.^ abcdefghijlefreelance.fr — Setting your freelance rates: calculating your day rate (2026): “To set your freelance rates, start from what you need to earn, not from what others charge.” ; “As a micro-entrepreneur, these expenses are not tax-deductible: they come out of your income, so they must be built into your rate.” ; “The hourly rate is derived from the day rate: divide it by 7.” https://lefreelance.fr/articles/fixer-ses-tarifs/ (accessed October 21, 2026)
Show 8 more sourcesShow less
- 4.^ abcdeclementine.fr — Freelance charges: the complete 2026 guide: “Not every working day can be billed to a client.” ; “This figure is essential, because the lower this number, the higher your daily rate must be to reach your income goal.” ; “Social contributions are calculated differently under micro-entrepreneur status, sole proprietorship, EURL, or SASU, with contribution levels specific to each structure.” https://www.clementine.fr/blog/comptabilite-social-et-juridique/les-charges-en-freelance/ (accessed October 21, 2026)
- 5.^Mira Knowledge — Writing and editing can be done while working internationally; it is the most asynchronous job, with the constraint being lower income due to AI rather than mobility. Verified on 09/16/2026: 2 concordant sources (perplexity.ai, hello-mira.com, hello-mira.com). https://www.perplexity.ai/search/840d8429-1de2-4d2a-892b-401b7a485927 (accessed September 16, 2026)
- 6.^Mira Knowledge — Translation and localization can be done while working internationally; highly asynchronous, they face contraction linked to AI (post-editing of machine translation). Verified on 09/16/2026: 2 concordant sources (perplexity.ai, hello-mira.com, hello-mira.com). https://www.perplexity.ai/search/840d8429-1de2-4d2a-892b-401b7a485927 (accessed September 16, 2026)
- 7.^Mira Knowledge — Content creation can be done as a digital nomad provided you organize bandwidth and equipment: heavy, regular uploads and a reliable connection are essential. Verified on 09/16/2026: 2 concordant sources (hello-mira.com, perplexity.ai, hello-mira.com). https://www.perplexity.ai/search/840d8429-1de2-4d2a-892b-401b7a485927 (accessed September 16, 2026)
- 8.^Mira Knowledge — Video editing and motion design can be done as a digital nomad provided you organize bandwidth and equipment: heavy footage to transfer and a powerful editing machine. Verified on 09/16/2026: 3 concordant sources (hello-mira.com, hello-mira.com, hello-mira.com). (accessed September 16, 2026)
- 9.^ abcdservice-public.gouv.fr — Income tax for a French citizen who moves abroad to live or work | Service Public: “If your tax residence is outside France, you are generally taxable only on your French-source income.” ; “If your tax household is based in France, you must pay income tax there, including on your foreign-source income.” ; “Even if you pay your taxes in France, check with the tax authority of your country of residence to find out your obligations regarding the income to declare and the taxes to pay.” https://www.service-public.gouv.fr/particuliers/vosdroits/F31442 (accessed October 21, 2026)
- 10.^ abcdediplomatie.gouv.fr — Taxation | France Diplomatie: “Your household (spouse or civil partner and children) remains in France, even if, due to professional requirements, you are temporarily required to stay in another country or for most of the year.” ; “You have the center of your economic interests in France.” ; “You are required to disclose the details of bank accounts (used or closed) opened abroad (form no. 3916, available online or on plain paper, to be attached to your income tax return no. 2042).” https://www.diplomatie.gouv.fr/fr/services-aux-francaises-et-aux-francais/vie-administrative-et-elections/fiscalite (accessed October 21, 2026)
- 11.^ abcdougs.fr — How to become a freelancer in 2026: complete guide: “Registration is done directly through the INPI single window, and you rely on the micro-social regime for your contributions.” ; “Creating your account on the Urssaf website is essential, as this body manages your social contributions.” ; “Separating your accounts offers a real advantage: a dedicated bank account simplifies management, especially for a micro-entrepreneur who must distinguish their flows once turnover exceeds €10,000 over two years.” https://www.dougs.fr/blog/comment-devenir-freelance/ (accessed October 21, 2026)